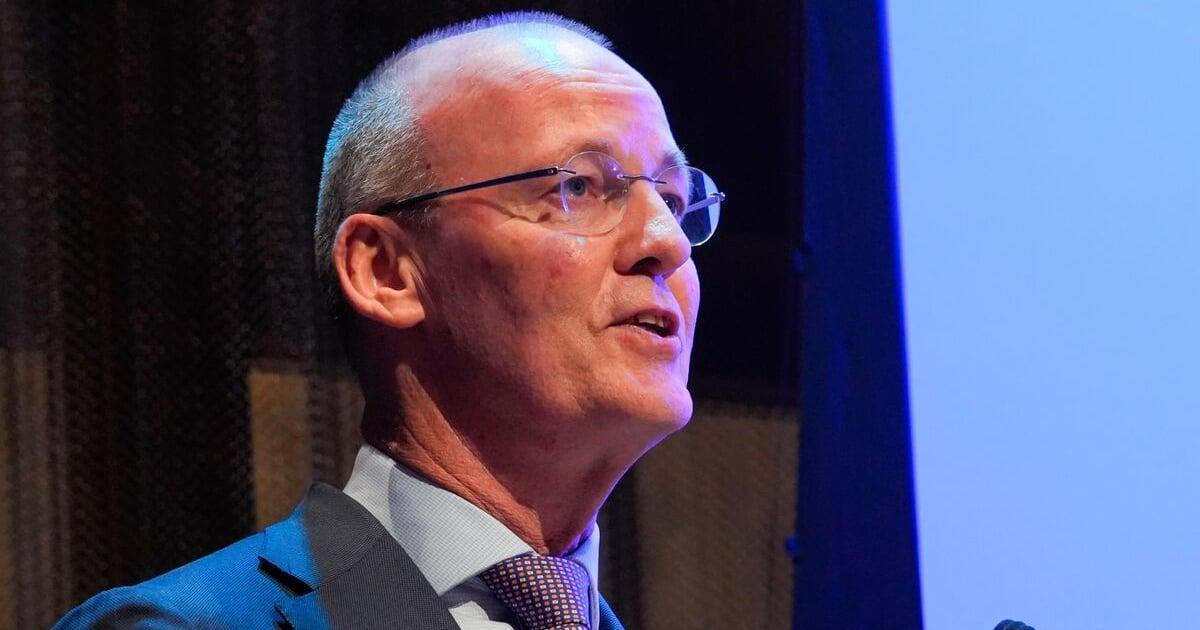
Klaas Knot has warned that the European Central Bank's crisis tools cannot replace disciplined public finances. The Dutch central banker, who is widely discussed as a possible successor to Christine Lagarde at the ECB, told Corriere della Sera that emergency bond-buying can calm disorderly markets but cannot fix underlying budget problems.
"There are situations where it is inevitable," Knot said in the interview published on Sunday. "The ECB can provide a shield in situations of disorderly market dynamics, but it cannot substitute for sound fiscal policy."
A signal on the ECB's limits
The remarks come at a sensitive moment for the euro area. Several member states are struggling with high debt levels, rising borrowing costs and political pressure to spend more on defense and energy transition. Investors have at times tested whether the ECB would step in to cap bond spreads, reviving memories of the 2012 "whatever it takes" pledge that calmed the sovereign debt crisis.
Knot's message is that such intervention has a narrow purpose. The bank's Transmission Protection Instrument and other facilities are designed to address market dysfunction, not to underwrite governments that run persistent deficits. Using them as a backstop for fiscal choices would blur the line between monetary and fiscal policy, he indicated.
A candidate for the ECB presidency
Knot has led De Nederlandsche Bank since 2011 and has served on the ECB's Governing Council for much of that time. He is known for a relatively hawkish stance on inflation and for emphasizing central bank independence. His name has circulated among governments and analysts as a contender to take the ECB's top job when Lagarde's term ends in October 2027.
The presidency is not directly elected by the public. European Union leaders nominate a candidate based on consensus among member states, and the European Parliament holds a non-binding vote. The choice typically balances nationality, policy views and managerial experience.
Fiscal pressure across the euro area
Knot's comments reflect broader concerns among central bankers about the sustainability of public debt in parts of the currency union. Italy, France and several other countries have deficits well above the EU's 3% of gross domestic product reference level. At the same time, demands for higher defense spending and green investment are making budget consolidation harder to sell politically.
The ECB has already raised interest rates from below zero to fight inflation, and while it has begun to lower them, borrowing costs remain far higher than during the decade of ultra-loose policy that followed the global financial crisis. That makes the cost of servicing debt more visible and more urgent.
What it means for investors
For bond markets, Knot's statement is a reminder that the ECB does not intend to cap yields indefinitely. Any future use of crisis tools would likely come with strict conditions and would be framed as addressing market dysfunction rather than funding governments. That leaves the risk premium on peripheral sovereign debt sensitive to fiscal news.
For the ECB succession race, the interview offers a clear view of how Knot would approach one of the institution's most delicate questions. His emphasis on fiscal responsibility suggests a presidency that would push governments to put their own houses in order before asking the central bank for help.
Outlook
The debate over the ECB's role in supporting sovereign debt is likely to intensify as the 2027 leadership decision approaches. Knot's position sets him apart from those who argue the central bank should play a more active role in stabilizing government finances, and it may appeal to countries in northern Europe that have long demanded fiscal discipline in the south.
Whether that message wins support among the EU leaders who will ultimately choose the next president remains to be seen. For now, Knot has made clear where he stands: the ECB can provide a shield, but it cannot write budgets.